How do I turn my savings into retirement income?
Turning savings, Social Security, and pensions into guaranteed* income that lasts.
Many people have savings. Fewer have a plan for turning those savings into income that lasts as long as retirement does. For more than 23 years, Jason Taylor has helped families and federal employees build that plan, one built around your whole financial life, not one account at a time.
Retirement isn’t one decision: it’s many that all touch each other. We look at the complete picture so each strategy supports the rest.
Turning savings, Social Security, and pensions into guaranteed* income that lasts.
A clear roadmap from where you are to the retirement you actually want.
The right mix for your timeline, adjusted as markets and life change.
When and how to claim, coordinated with the rest of your income.
Keeping more of what you’ve saved through tax aware withdrawal sequencing.
Protection that fits your plan, offered through Ascend Financial Advisors.
*Guaranteed lifetime income available through annuitization or the purchase of an optional lifetime income rider, a benefit for which an annual premium is charged. Annuities are long-term, tax-deferred vehicles designed for retirement and contain some limitations.
On average, Social Security replaces about 40% of pre-retirement earnings, according to the Social Security Administration. The rest has to come from a plan, and what that plan looks like depends on where your career happened.
FERS, TSP, survivor benefits: the federal system has its own rules, and getting one piece wrong can cost you for the rest of retirement. Jason has worked with federal employees since 2007, presenting at agencies including the VA, BLM, Bureau of Reclamation, BOP, Postal Service, and FAA, and co-authored The Smart Fed Retirement Handbook.
401(k)s, IRAs, a business you built, equity you earned: your savings live in different accounts with different tax rules, and retirement is when they all have to start working together. We help families turn what they’ve built into income that lasts.
What does that mean? Your portfolio starts with a base strategy built around your goals and timeline. That part doesn’t change with the news cycle. What does change is how we position within it, adjusting as market momentum shifts. Disciplined, not reactionary: we move when the data moves, not when the noise does.
“You want to have a base strategy. But from there we adjust depending on the momentum of the markets. We’re not reactionary.”
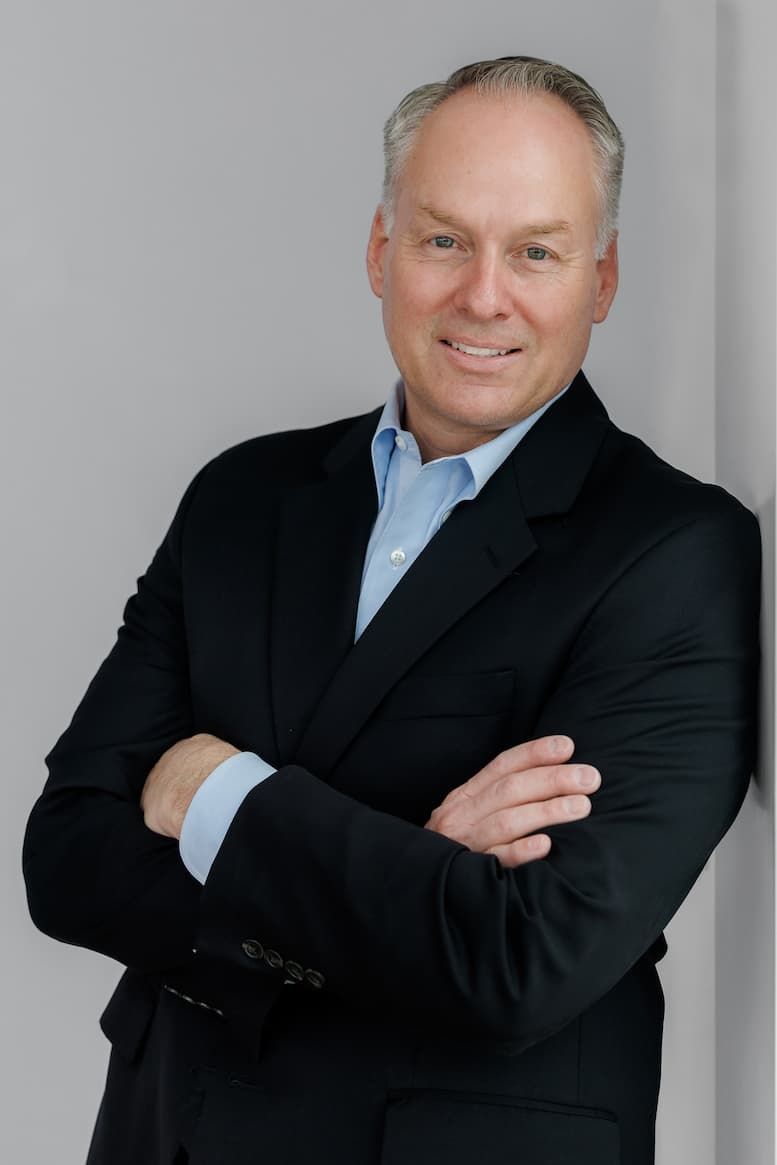
Wealth Management Advisor · Retirement Income Specialist · Certified Federal Employee Benefits Consultant
Jason has spent 23+ years helping families organize their finances and build strategies for the future. He’s based in Eagle, Idaho, and works with clients throughout the Pacific Northwest, Nevada, Arizona, and Utah. He is president of Ascend Wealth Management and Ascend Financial Advisors, and co-author of The Smart Fed Retirement Handbook.
Review our ADV Part 2A and Form CRS, or verify Jason’s registration through the SEC’s Investment Adviser Public Disclosure site.
More about Jason →We talk about where you are, where you want to be, and whether we’re the right fit.
We build your retirement income plan around your complete picture: investments, Social Security, tax efficiency strategy, insurance, and (for federal employees) your federal benefits.
Markets move and life changes. We review together and adjust on momentum, not emotion.
Nothing. The initial consultation is no-cost, and its purpose is fit — for both of us.
No. Jason is based in Eagle, Idaho, and works with clients throughout the Pacific Northwest, Nevada, Arizona, and Utah, meeting by phone or video.
No. Federal employees are a specialty, but Jason works with families and pre-retirees from all backgrounds.
Advisory services are provided under a fiduciary duty through Ascend Wealth Management LLC. Insurance and annuity products are offered through Ascend Financial Advisors, an affiliated company, and may pay a commission. Full details are in our ADV Part 2A and Form CRS.
You generally have options: leave it where it is, move it into an IRA, or begin drawing from it directly — each with different costs, investment choices, and tax consequences. The right move depends on your income plan, not a default.
No. The levers change — claiming strategy, withdrawal order, and tax sequencing matter more than savings rate at that point — but they’re real levers, and coordinating them is exactly what a plan is for.
It’s a bridge payment for many FERS employees who retire before 62 with an immediate annuity, designed to approximate the Social Security earned during federal service until you can claim at 62. Eligibility and amount depend on your age, years of service, and retirement type — it’s one of the first things checked in a federal retirement plan.
That’s exactly the reason to have a conversation.
Schedule your no-cost consultation